

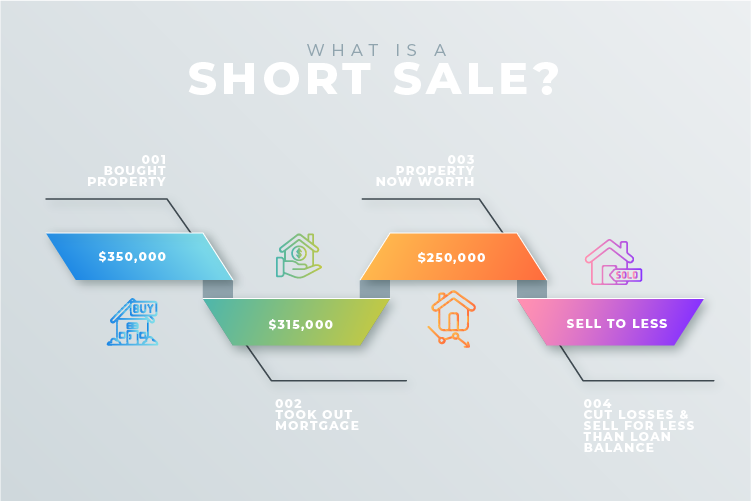
Understanding Short Sales
Testimonials
"
Usman was a tremendous help to me throughout the entire purchase process. I had begun looking before the pandemic and when that hit, I stopped looking but Usman never stopped working for me and helping to keep me up to date with the latest events in the market. If you need a home in Florida or have one to sell, contact Usman for exceptional results and professionalism.
Positive
Responsiveness, Professionalism
"
- Bill Owen
"
5-Stars
"
- Patsyann Smith
"
My wife and I had such a great selling and buying experience with Usman! He is knowledgeable, personable, and made himself available anytime we needed him. He truly made us feel like we were his only clients and his top priority. I can’t recommend him strongly enough!
"
- P W
"
If you are looking for a realtor that you can depend and trust on look no further! Usman is by far the best realtor I have ever had! He has been attentive and professional when going above and beyond to help me sell my home. I look forward to working with him in the future.
Thanks again Usman, you made this process simple, easy, and stress free!!
"
- Josiah Mckelvey
"
Usman was a pleasure to work with and was one of the best agents I’ve ever done business with. He is very responsive to emails/messages and was able to procure a tenant for my rental in record time. I will definitely be using him in the further for any rental needs. Highly recommended!
"
- Kevin Mathew
"
Usman was a joy and a real pleasure to work with. He is extremely professional and knowledgeable. His help and guidance throughout the whole process was excellent. We would definitely work with him again and would 100% recommend him.
"
- Andrea
"
I highly recommend our realtor Usman. He was always available when we had questions, and believe me we had questions. We love our house! When we go to sell our trailer we definitely will use Ysman Murtaza again.
Positive
Responsiveness, Quality, Professionalism, Value
"
- Laura Baker
"
Very knowledgeable person, who was also helpful in coordinating my home purchase remotely.
"
- jake francis
"
Usman was amazing to work with! Thanks to him I was able to purchase my new home at an amazing price!
"
- Jonathan Spencer
"
Our realtor Usman was very professional , as he answerer all of our questions and concern on our new purchase in ocala, very promt in getting back to us on every little detail of our purchase,since we were from central ny is was almost as we had a friend looking out for our needs on our relocation to to the ocala florida area. Highly recommend him to anyone and would do business with foxfire real estate again in the furure. Thank you for all your help in obtaining our new home
Ken and Kathy River.
Positive
Responsiveness, Quality, Professionalism, Value
"
- Kenneth River
"
It was an absolute pleasure working with Usman. He is professional, knowledgeable and kept us well informed. It was a smooth process. Highly recommend. Thank you so much Usman.
"
- Jeannie W


 Copyright © MFRMLS.com All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information on this site was last updated Last updated on September 21, 2026 9:25 AM UTC The listing information on this page last changed on Last updated on September 21, 2026 9:25 AM UTCd. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of MFR MLS.
All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Updated on September 21, 2026 9:25 AM UTC
 he information contained herein has been provided by REALTORS® Association of Citrus County, Inc. This information is from sources deemed reliable but not guaranteed by REALTORS® Association of Citrus County, Inc. The information is for consumers' personal, non-commerical use and may not be used for any purpose other than identifying properties which consumers may be interested in purchasing. The information contained in this web site is believed to be reliable but is not guaranteed.
